Economic Order Quantity (EOQ) is the most commonly taught method for sizing orders in the most cost-effective manner, but it often falls short of producing optimal financial results for companies in the real world. The reason is two-fold.
One, it is not impacted significantly by the price paid per item, leading to suboptimal results when sizing-driven price breaks are offered. The solution for this is known; we will cover it in the interest of completeness of the discussion.
Two, it is often not aligned with what the finance teams in businesses actually want to see out of the inventory management teams when the solution to the first issue is applied. In this article I will present a simple, novel analysis that can lead to better alignment between the inventory management and finance teams by calculating an Inventory Price Efficiency (IPE). An example analysis (Excel) will be provided as a template.
To refresh, EOQ is defined as:
EOQ = √( (2 * D * S) / H )
where:
D= Annual demand in unitsS= Cost per order (typically calculated by total procurement and receiving costs divided by lines ordered and received annually)H= Variable holding cost per year per item
Before moving on it is important to note that H is defined purely as the variable holding costs. We cannot take inventory to zero, so there will always be the warehouse, management, utilities, etc. Variable holding cost is primarily driven by the Weighted Average Cost of Capital (WACC) for the business, which should be obtained from the finance team and is expressed as a percentage of inventory value which can then be applied per unit. The second component of H is material handling labor, inventory insurance, etc., and is commonly approximated as 1% - 3% of inventory cost depending on the nature of the business. Determining exact values for this component is not necessary as it will not significantly impact the decisions made. You can verify this by changing it in the example analysis. Many companies introduce errors by including fixed overhead and stating holding costs in the 25%+ range. Unless you truly could operate your business with no inventory this is not correct.
The implied assumption in EOQ is that price is fixed, which is not true in many cases where volume driven price breaks are offered based on Minimum Order Quantities (MOQs). The solution to this is well known:
- Calculate the EOQ at each price point (
P). - Determine the Total Annual Cost (TAC) for each price point using the greater of the EOQ and MOQ, which is then defined as
Q. - Select the option with the lowest TAC.
With TAC defined as:
TAC = Annual Ordering Cost + Average Holding Cost + Annual Material Cost + Reserve Impacts
Annual Ordering Cost (AOC) is the number of orders placed per year multiplied by the cost per order:
AOC = D * S / Q
Average Holding Cost (AHC) is the average cost of holding one order:
AHC = Q * H / 2
Annual Material Cost (AMC) is simply price times annual demand:
AMC = P * D
Reserve Impacts occur when order sizes would put inventory levels on receipt of the order above company policy levels, triggering financial reserves, or beyond the expiration life of the product if there is one. An example is shown in the example analysis but these vary by company and do not have a standard impact. As a rule, any order that triggers a reserve impact will never be the optimal solution.
Putting these together:
TAC = ( D * S / Q ) + ( Q * H / 2 ) + ( P * D ) + Reserve Impacts
Then select the option with the lowest TAC and we have found the “optimal” solution for accounting for MOQ price breaks in order sizing, and this work is all well-known. But this often results in unhappy finance and warehouse teams as price breaks drive inventory up easily in this analysis.
Which leads to the novel additional analysis that can lead to “non-optimal” order quantities producing results that the business prefers, by calculating Inventory Price Efficiency (IPE):
IPE = Discount / ( Q / EOQ )
where:
Q= Order quantity (max of EOQ and MOQ)EOQ= Economic Order Quantity at that price pointDiscount= The percentage discount off the smallest order size possible
IPE measures the efficiency at which further inventory gets you more discounts. The higher the IPE, the more discount each increment of inventory is earning.
In the example analysis it is shown that two options are very close on TAC. But one of them has a significantly higher IPE. In the example shown there is $33,000 more inventory held on average for a total annual cost reduction of $1,363. In practice, every finance team I’ve worked with has preferred the working capital improvement over the total cost improvement in that situation given their magnitude. In fact, IPE has proven, in my personal experience, to be the most accurate predictor of what finance teams actually want their inventory management teams to do when optimizing order sizing.
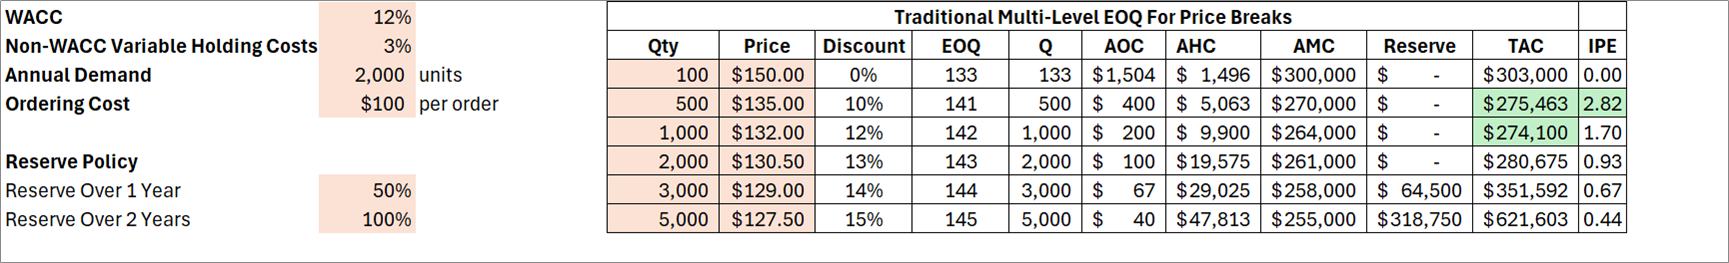
The example analysis. Ordering 500 and ordering 1,000 are within $1,363 in annual total cost, but the 1,000 option doubles average inventory. Download the Excel file to try your own numbers.
Summary
EOQ is the standard method for sizing orders, but it ignores volume price breaks, and once those are accounted for it often recommends order sizes that finance teams do not want. The well-known fix is to calculate EOQ at each price point and compare total annual cost using the larger of EOQ and MOQ. This article adds a simple measure, Inventory Price Efficiency (IPE), which shows how much discount each increment of additional inventory actually earns. In the example analysis, two order sizes are within about $1,400 in annual total cost, but one doubles the average inventory on the balance sheet. IPE makes that trade-off visible and, in practice, has been the best predictor of what finance teams want from order sizing decisions. The example analysis is available as an Excel template.